October 2026 Developers’ Sales: Sharp Rebound in New Home Transactions Kickstarts Final Quarter of the Year
Research16 Nov 20268 min read

In October 2026, developers sold a total of 1,716 private homes (excluding ECs). This painted a stark contrast to September’s lower sales total of just 296 units sold and represents a 497.7% month-on-month (m-o-m) increase in the number of private homes sold on the primary market.
The surge in transactions sold was largely due to two highly-anticipated launches, Lucerne Grand located at Lakeside in the Outside Central Region (OCR), as well as the long-awaited redevelopment Thomson Reserve in the Rest of Central Region (RCR). With a positive take-up of 61% and 90% on their respective launch weekends, the tandem of new projects accounted for 82.9% of all units sold on the primary market in October.
Freehold District 11 project The Serra Residences also made its debut in the month, selling 25 of its 133 units (18.8%). Notably, five, or one-fifth of the units that changed hands were luxury homes, including a penthouse sold in excess of $11 million, making it the priciest new non-landed private home transaction for October. This points to continued demand for larger, more exclusive homes in the Core Central Region (CCR).
Sales were supported by a greater influx of new private homes, which totalled 2,058 units, a significant 1,202.5% m-o-m increase from September, which saw only 158 units launched. Fresh supply primarily consisted of new units launched at Lucerne Grand, Thomson Reserve, Dunearn House and The Serra Residences.
Within the Executive Condominium (EC) segment, developers sold 15 new units, reflecting a 34.8% m-o-m decline, with buyers snapping up balance stock from ECs launched earlier in the year.
Table 1: New home sales over the last six months (excluding ECs)
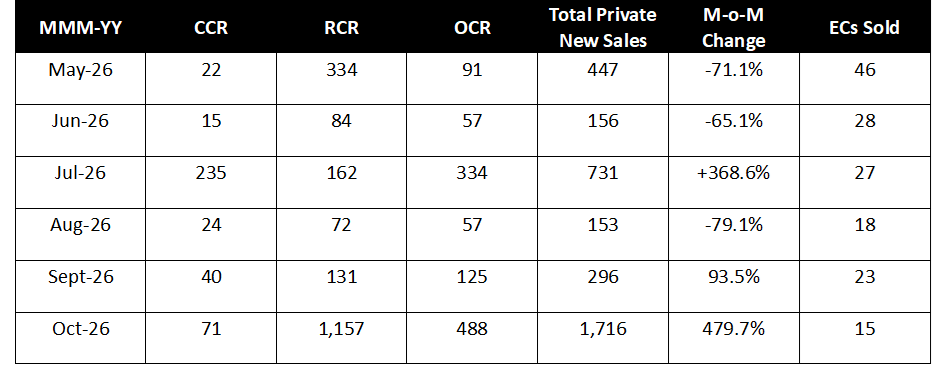
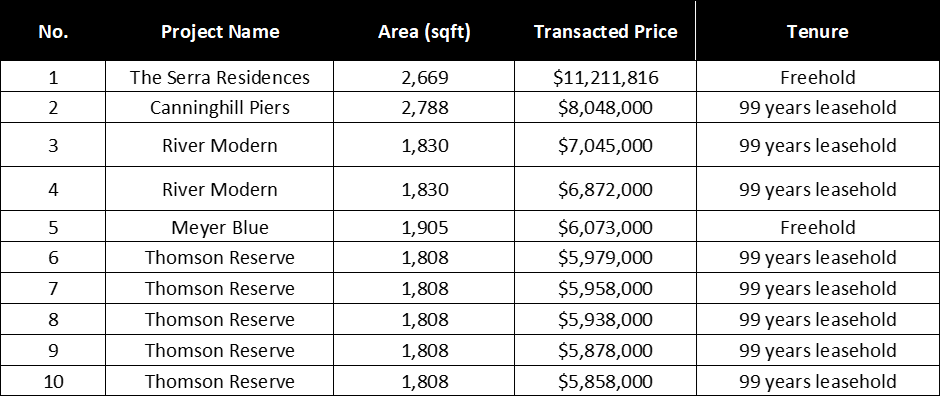
Table 2: Top performing new non-landed projects in October 2026 (excluding ECs)
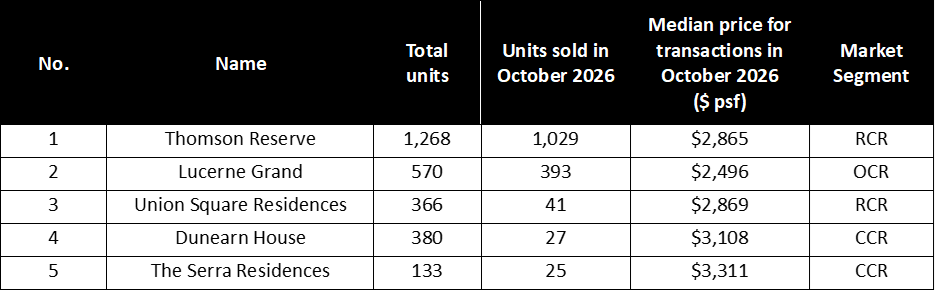
Strong Take-Up at Thomson Reserve Reflects Demand for Well-Located, Larger Homes
Thomson Reserve was the best-selling new launch of October, with 1,029 of its 1,268 units sold during the month with a median price of $2,865 psf. Demand was broad-based, with all three- and four-bedroom apartments and nearly all five-bedroom suites sold out.
The overall response to the launch of Thomson Reserve points to demand from buyers seeking larger homes in an established neighbourhood. Its location near Upper Thomson MRT, schools, nature parks and the Upper Thomson dining stretch supported the appeal. At the same time, starting prices of $1.544 million for two-bedroom units and $2.503 million for three-bedroom units helped keep the purchase quantum within reach for genuine owner occupiers.
Since launching in October, all 200 two-bedroom-plus-study units have been sold. Priced between $2 million to $2.5 million, they fell within the “sweet spot” for many upgraders seeking a home in an RCR location, contributing to the swift take-up.
Together, the result suggests that projects combining an established location, MRT access, varied unit sizes and manageable entry prices can attract strong demand. We can expect to see the balance 125 units snapped up over the coming few months, ahead of the launches of similar large city-fringe developments such as One Chuan Grove in 2027.
Lucerne Grand: Connectivity and Jurong’s Transformation Support Buyer Demand
Lucerne Grand sold 393 of its 570 units (68.9%) in October, at a median price of $2,496 psf. The 570-unit development is the first new private residential launch near Lakeside MRT in a decade, following Lake Grande in 2016.
Two-, three- and four-bedroom units all saw positive take-up among buyers, with standard two-bedroom and four-bedroom premium apartments among the best-performing types.
Pent-up demand aside, buyers were also largely drawn in by its immediate proximity to Lakeside MRT station and Jurong Lake District (JLD), which is slated to be a major employment hub in the West.”
The JLD’s longer-term development could also stoke future housing and rental demand within the Lakeside area, as more job opportunities emerge. For forward-looking investors, these prospects could be appealing as they seek to position themselves ahead of the JLD’s completion and a larger resident base.
Moreover, families may have been drawn to its location within a 1-km radius of four primary schools, namely Boon Lay Garden Primary School, Rulang Primary School, Lakeside Primary School, and Shuqun Primary School.
Centrally Located Projects Continue to Pull Demand
Other projects that featured in the top five transactions for the month included Union Square Residences, Dunearn House, and the newly-launched The Serra Residences.
Together, the three projects accounted for 93 sales, or nearly a third (31.6%) of the remaining 294 new homes sold across projects other than Thomson Reserve and Lucerne Grand.
Notably, more than a quarter (28) of the units sold at Union Square Residences, Dunearn House and The Serra Residences were priced below $2 million, mainly comprising one- and two-bedroom layouts. Based on caveats data, units under 800 sq ft at these projects achieved a median price of $2,930 psf, just 3.3% above the $2,836 psf median for similarly sized units at Thomson Reserve, which sold out at launch.
For buyers comparing the projects, this modest price premium may have made the city-centre locations more attractive for investment. Those seeking rental income may have considered the potential benefits of being closer to the city worth the additional outlay, particularly for smaller units that are generally more accessible to investors.
Around 36, or 38.7% of the units sold at these three projects were 3-bedroom or larger homes priced above $2.9 million. This included five luxury home transactions (exceeding $5 million) at The Serra Residences. These sales point to sustained demand for larger, liveable homes in central locations, particularly among Singaporean owner-occupiers. Buyers continue to value the convenience of established amenities and transport links, as well as the longer-term potential of ongoing infrastructure improvements and rejuvenation in central areas.
New EC Sales Remain Soft as Buyers Await Fresh Options
In October, developers sold 15 new ECs, representing a 34.8% m-o-m downtick from the low base of 23 units sold in September.
Coastal Cabana continued to lead new EC transactions for the fifth consecutive month with 14 units sold at a median price of $1,820 psf. Rivelle Tampines, which launched in March, accounted for the sole other EC unit sold in the month.
Chart 1: Number of unsold EC units and EC units sold
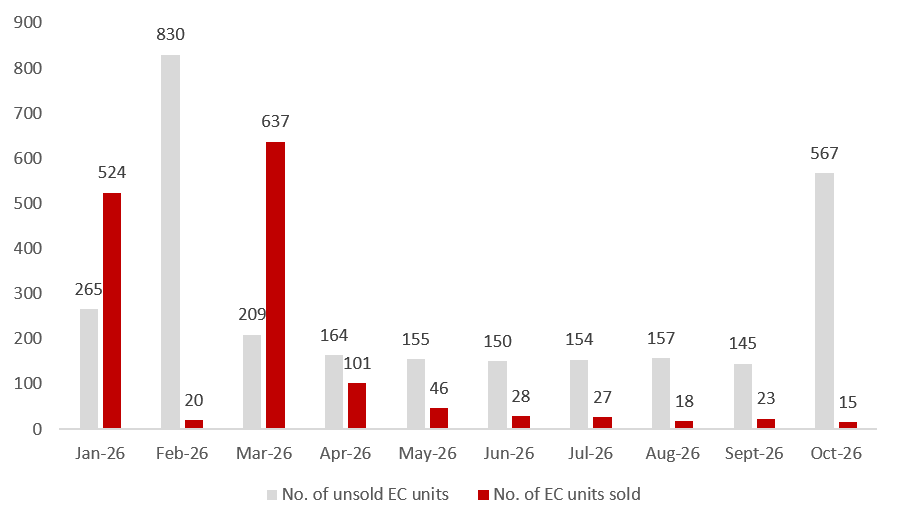
Excluding the incoming supply of 430 units at Wynwood Grand, 137 EC units remain unsold as of end-October. This tight inventory is likely to keep new EC sales muted until future launches reignite buyer interest with fresh options in both layouts and locations.
Wynwood Grand, the next EC project to launch, is slated for a 1Q 2027 preview. It could draw strong interest from HDB upgraders and first-time buyers as the first EC development in the Woodlands planning area in more than a decade. The project will comprise 420 units and is among the last projects to come under the previous EC rules, including a five-year Minimum Occupation Period and access to the Deferred Payment Scheme.
Buyer Profile
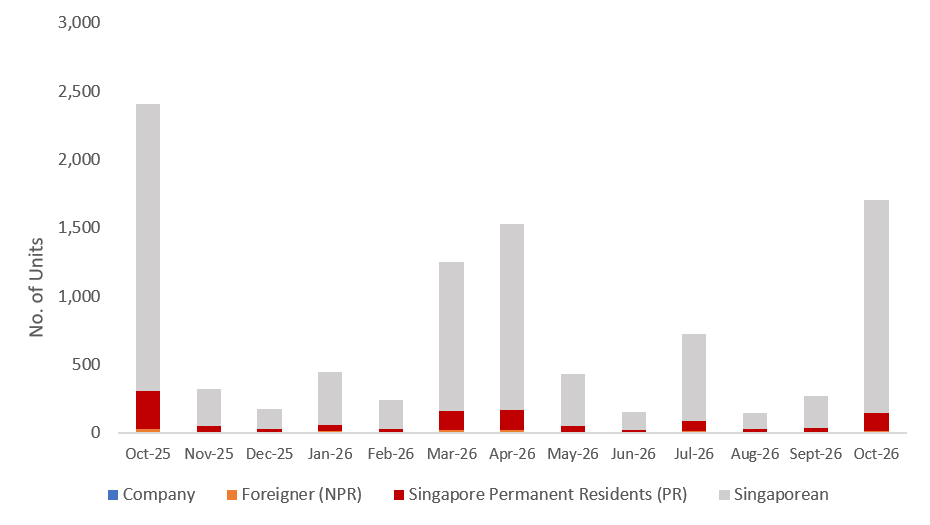
Singaporean Citizens continued to dominate new non-landed private home purchases (excluding ECs) in October, making up 91.6% of transactions, or 1,562 units, according to URA caveat data as at 15 November 2026. Permanent Residents accounted for 132 units, or 7.7% of transactions.
The 60% Additional Buyer’s Stamp Duty (ABSD) continued to dampen foreigner demand. Only 11 foreign purchase was recorded in October, representing 0.6% of total transactions. Although foreign participation remained minimal, Singapore’s stable and transparent real estate market should continue to attract overseas buyer interest over the longer term.
Luxury Homes
Chart 3: Buyer profile for non-landed private homes (excluding ECs) transacted at $5mil and more
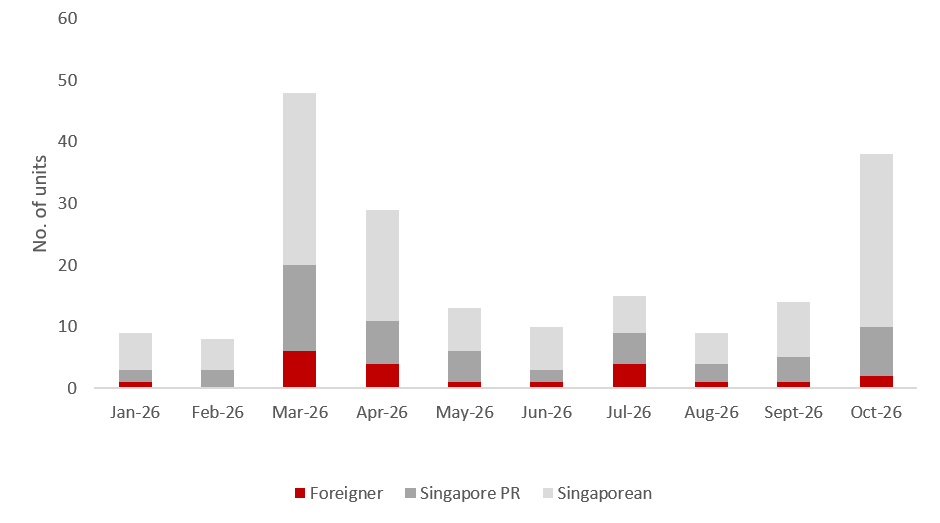
Non-landed luxury home transactions (excluding ECs) valued at $5 million and above rose to 38 deals in October, up from the 14 transactions recorded in September. Singaporeans and Permanent Resident (PR) buyers accounted for 36 deals in October, of which 28 were made by Singaporeans and eight by PR buyers.
The priciest deal in the non-landed segment involved a 2,670 sq ft penthouse unit at The Serra Residences, which was purchased by a PR for $11.2 million ($4,200 psf). This was followed by a 2,788 sq ft unit at Canninghill Piers, which sold for $8.05 milllion ($2,887 psf), and a 1,830 sq ft unit at River Modern that was purchased for $7.05 million ($3,850 psf).
A Singaporean buyer accounted for October’s overall priciest new private home transaction, having purchased a 4,360 sqft freehold detached house at Bournemouth Road for $15.7 million ($3,601 psf).
Table 3: Top luxury non-landed private home (excluding ECs) transactions for October 2026
Closing Thoughts and Forecast
Based on advance estimates released by the Ministry of Trade and Industry (MTI), Singapore’s economy continued to grow in 3Q 2026, albeit at a more measured pace of 5.4% year on year. Housing demand should remain supported by healthy household balance sheets and a growing population, even amid headwinds such as softer employment conditions, and inflation driven by higher energy costs.
As it stands, October’s sharp rebound in developers’ sales also shows that underlying buyer appetite for new private homes remains intact. Demand should therefore stay firm for the foreseeable future, provided local households remain financially resilient, and Singapore continues to retain its safe-haven appeal among investors.
However, monthly new private home sales could taper off for the rest of this year, both due to the approaching holiday season and lack of major new launches till early-2027. Given the strong pipeline of upcoming launches next year, some buyers may also choose to hold off their purchases for now.
Against this backdrop, ERA Singapore expects new private home sales (excluding ECs) to reach around 9,000 units by year-end, barring any unforeseen circumstances.